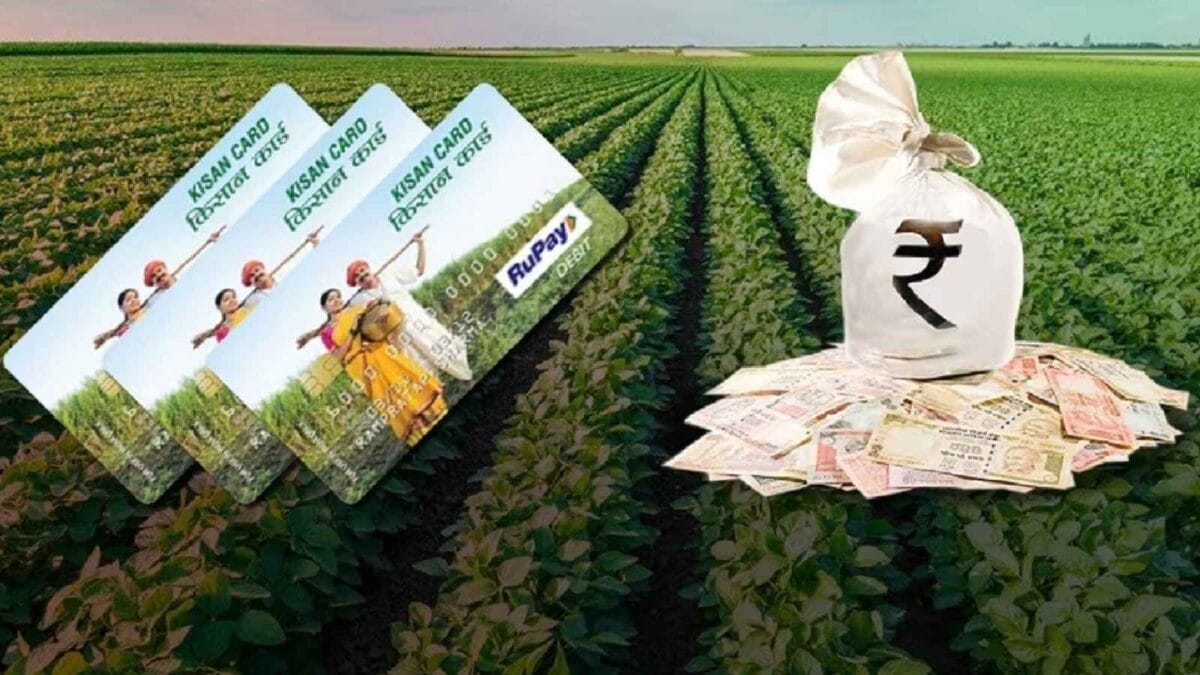
1 / 8 The Kisan Credit Card, or KCC, helps farmers access timely credit for agriculture and related activities.
Instead of depending heavily on moneylenders and paying high interest, eligible farmers can use formal bank credit for their farming needs.
(Image: File Photo/ News18)ADVERTISEMENT3 / 8 The KCC loan limit has increased over the years.
(Image: File Photo/ News18 Hindi)6 / 8 If a KCC loan remains unpaid for a prolonged period, the bank can begin recovery proceedings.
(Image: File Photo/News18 Hindi)ADVERTISEMENT7 / 8 A default does not simply mean that a farmer’s land is immediately auctioned.
Last Updated: September 15, 2026, 18:45 IST
For many farmers, arranging money for seeds, fertilisers, irrigation and other farming expenses can be a major challenge. The Kisan Credit Card (KCC) was introduced to provide easier access to agricultural credit. But what happens when a farmer fails to repay the loan? Can the bank seize the land?
1 / 8 The Kisan Credit Card, or KCC, helps farmers access timely credit for agriculture and related activities. The facility can be used for expenses such as seeds, fertilisers, irrigation, harvesting, animal husbandry and fisheries, reducing dependence on informal lenders. (Image: File Photo/ News18)
2 / 8 The Kisan Credit Card scheme was launched in 1998 to make agricultural credit easier and more affordable. Instead of depending heavily on moneylenders and paying high interest, eligible farmers can use formal bank credit for their farming needs. (Image: File Photo/ News18)
ADVERTISEMENT
3 / 8 The KCC loan limit has increased over the years. According to the information in this report, the limit for crop loans has been raised from Rs 3 lakh to Rs 5 lakh. Agriculture-related activities such as animal husbandry and fisheries can also receive credit. (Image: File Photo/ News18)
4 / 8 Another important KCC feature is collateral-free credit. The collateral-free loan limit has been increased to Rs 2 lakh, according to the information provided. This can make formal credit more accessible to farmers who may not have assets available as security. (Image: File Photo/ News18 Hindi)
ADVERTISEMENT
5 / 8 KCC works differently from a typical monthly EMI loan. Farmers generally have a repayment cycle linked to their agricultural needs and loan terms. Interest and principal repayment requirements depend on the facility and applicable rules, so borrowers should check their bank’s conditions. (Image: File Photo/ News18 Hindi)
6 / 8 If a KCC loan remains unpaid for a prolonged period, the bank can begin recovery proceedings. Continued default may lead to legal action and recovery measures against the borrower. The exact process depends on the loan terms, applicable laws and the individual case. (Image: File Photo/News18 Hindi)
ADVERTISEMENT
7 / 8 A default does not simply mean that a farmer’s land is immediately auctioned. Depending on the circumstances, applicable security arrangements and legal recovery procedures, a bank may pursue secured assets. Any attachment or sale must follow the relevant legal and administrative process. (Image: File Photo/ News18 Hindi)