Or would a big rally in the S&P 500 bring a hike because it’d be a signal that financial conditions are too loose?
The only scenario I can imagine where the Fed might hike is if there’s a surprise peace deal with Iran.
There’d be a material easing in financial conditions and I can see how the Fed might want to push against that.
On the surface, this might look like it could push the Fed to hike, but I don’t think so.
If anything, financial conditions would be tightening sharply, so the last thing you’d want to do is hike.
Thank you for subscribing to my posts. If you’re not yet a paying supporter, please consider becoming one. That’ll allow you to DM me with questions and comments. Your contribution will help cover the cost of the data I use in my posts, which I fund out of my own pocket. Thanks so much for your support and feedback!
I think the Fed stays on hold next week, but it’s always a good idea to think through what could happen in the coming days for this to change. Would a sharp spike in oil prices change the picture because the Fed might want to get ahead of the next supply shock? Or would a big rally in the S&P 500 bring a hike because it’d be a signal that financial conditions are too loose?
The only scenario I can imagine where the Fed might hike is if there’s a surprise peace deal with Iran. Oil prices would fall very sharply and long-term bond yields would tumble. There’d be a material easing in financial conditions and I can see how the Fed might want to push against that. But I think we can all agree that a peace deal before the midterms is very unlikely. The only way for that to happen would be for the US to agree to Iran’s terms and the probability of that is zero before November 3.
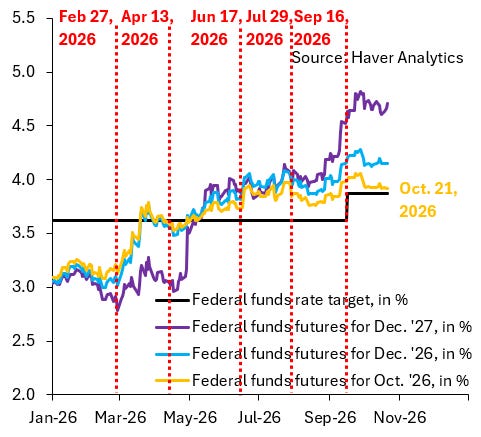
Before I think through scenarios, let me say a few words about markets. I’m surprised how docile markets are going into next week. I say this because we went into the Fed meeting on July 29 pricing ten basis points for a hike after a core CPI reading that was flat just a few weeks before. Now - as the orange line in the chart above shows - we’re pricing four basis points after a CPI that was arguably “hot,” i.e. we’re pricing next to nothing. Market psychology has fundamentally changed from a few months ago and maybe that’s thanks to the unanimous September hike, which has put to bed - at least for now - all the hand-wringing about Fed credibility. This shift in psychology means staying on hold is relatively costless now, in contrast to July 29 when it sparked a bond market tantrum that only ended with the surprise Treasury buyback announcement on August 19 and the hawkish pivot from Warsh at Jackson Hole on August 28.
So let’s think through scenarios. First, let’s imagine a spike in Brent to $125 from $110 at the moment. On the surface, this might look like it could push the Fed to hike, but I don’t think so. The debt crisis in France would escalate sharply, anxiety around all the AI and data center debt would increase and the S&P 500 would tumble. That just isn’t a setting where the Fed is itching to hike. If anything, financial conditions would be tightening sharply, so the last thing you’d want to do is hike. Second, let’s imagine a surprise peace deal that sends oil prices down to $85 with more declines likely. This would see financial conditions ease drastically. Long-term yields would fall and the S&P 500 would stage a big rally. While I’d love to see this scenario and the Fed might well hike to keep financial conditions from easing too much, this just isn’t going to happen before November 3. The US would need to agree to Iran’s conditions at this point and that’s a probability zero event before the midterms.
They say to let sleeping dogs lie. The market is in a docile mood at the moment. We should all just go with that and resign ourselves to no hike on October 28. There’ll be plenty more messy Fed meetings and stand-offs like on July 29, just not next week.