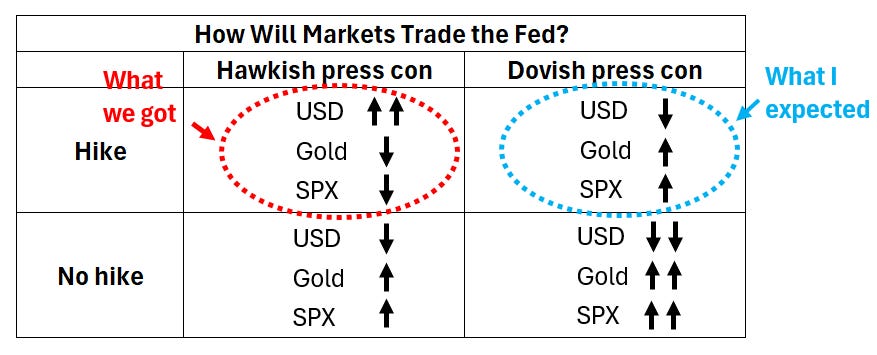
a dovish hike, while we ended up in the top left.
When you’re wrong, the most important thing is to figure out why so you don’t repeat your mistake.
This is all about sticking it to Trump and - perhaps - sticking it to Warsh.
Warsh told us at Jackson Hole he’s leaning hawkish and that’s what happened.
As Warsh said yesterday, he doesn’t put much weight on individual data points.
Thank you for subscribing to my posts. If you’re not yet a paying supporter, please consider becoming one. That’ll allow you to DM me with questions and comments. Your contribution will help cover the cost of the data I use in my posts, which I fund out of my own pocket. Thanks so much for your support and feedback!
I got yesterday’s Fed decision completely wrong. While I expected a hike, I thought everything else would lean dovish. That wasn’t the case. The hike was unanimous. I didn’t see that coming. I thought there’d be at least one or two dissents. The median “dot” in the Summary of Economic Projections has two hikes for 2026 - I thought we’d get “one-and-done” - and the “dots” for 2027 are close to indicating more tightening next year. There was nothing dovish about yesterday. The signal is for a hiking cycle that looks like it might be one 25 basis point hike per quarter for two more quarters, i.e. it fully reverses the three cuts made last year under then Chair Powell.
When you make a mistake as a forecaster, it’s important to be upfront about this and own it. In the chart below, I thought we’d end up in the top right corner, i.e. a dovish hike, while we ended up in the top left. When you’re wrong, the most important thing is to figure out why so you don’t repeat your mistake. Here’s my conclusions so far:
This is a narrative - not a framework - Fed: in the press conference, Chair Warsh was asked one of the key questions I’d flagged yesterday, which is what’s changed from July 29 when he was dovish. His response was that growth has strengthened, that inflation didn’t show signs of slowing fast enough and that geopolitics flared up again. This stuff is all really loosey-goosey. Last Friday’s CPI was distorted by one-off price hikes. Once you set those aside, underlying inflation is slowing fast. As far as geopolitics goes, oil prices spiked just before the July 29 meeting, so this also isn’t an obvious differentiator. The whole point of the press conferences is to have journalists poke holes in the Fed’s story and that didn’t happen yesterday. It turns out the press conference was tightly choreographed as the tweet below from veteran Fed Watcher Howard Schneider suggests. When you’re doing narratives - not frameworks - things are way more flimsy, so you don’t want to be getting lots of questions. Of course, this shift mirrors the big picture, since the Trump administration also doesn’t love getting quizzed on stuff.
Without a framework, you can flip flop: Warsh gets panned for his performance at the July 29 press conference, but you have to remember that core CPI was flat just two weeks before that meeting, so his relatively dovish inflation commentary made perfect sense at the time. What’s actually harder to explain is the abrupt shift since then. In my opinion, the only real explanation is the spike in long-term yields after July 29, which made another dovish performance impossible. The narrative shift is therefore just a means to an end, which in this instance is to keep long-term yields anchored. The implication is that the narrative can change abruptly as the situation dictates. This is a completely different Fed.
Forget unanimity: much is being made of the unanimity in the rate hike decision and the broad shift up in the “dots.” The chart above shows their evolution from March to June and now yesterday for 2026 on the left and for 2027 on the right. I think this is a red herring. I’m almost certain that many of the folks who are now hawkish would still be dovish and against hikes if Jay Powell were still the Chair. This is all about sticking it to Trump and - perhaps - sticking it to Warsh.
The key takeaway for me is to not overthink this Fed. Warsh told us at Jackson Hole he’s leaning hawkish and that’s what happened. I had pictured him agonizing over the finer points of Friday’s CPI. That’s - at the most basic level - what I got wrong. As Warsh said yesterday, he doesn’t put much weight on individual data points.